
A customer signs a $24,000 annual contract on Monday. Your hosting bill clears on Tuesday. Payroll goes out Friday. The customer’s accounts-payable team plans to send the first payment in 45 days.
On a sales dashboard, Monday was a good day. In your bank account, nothing happened. That gap matters when you have no investor funding to cover it. For a tiny company, getting paid is not administrative cleanup after the sale. It is part of making the sale work.
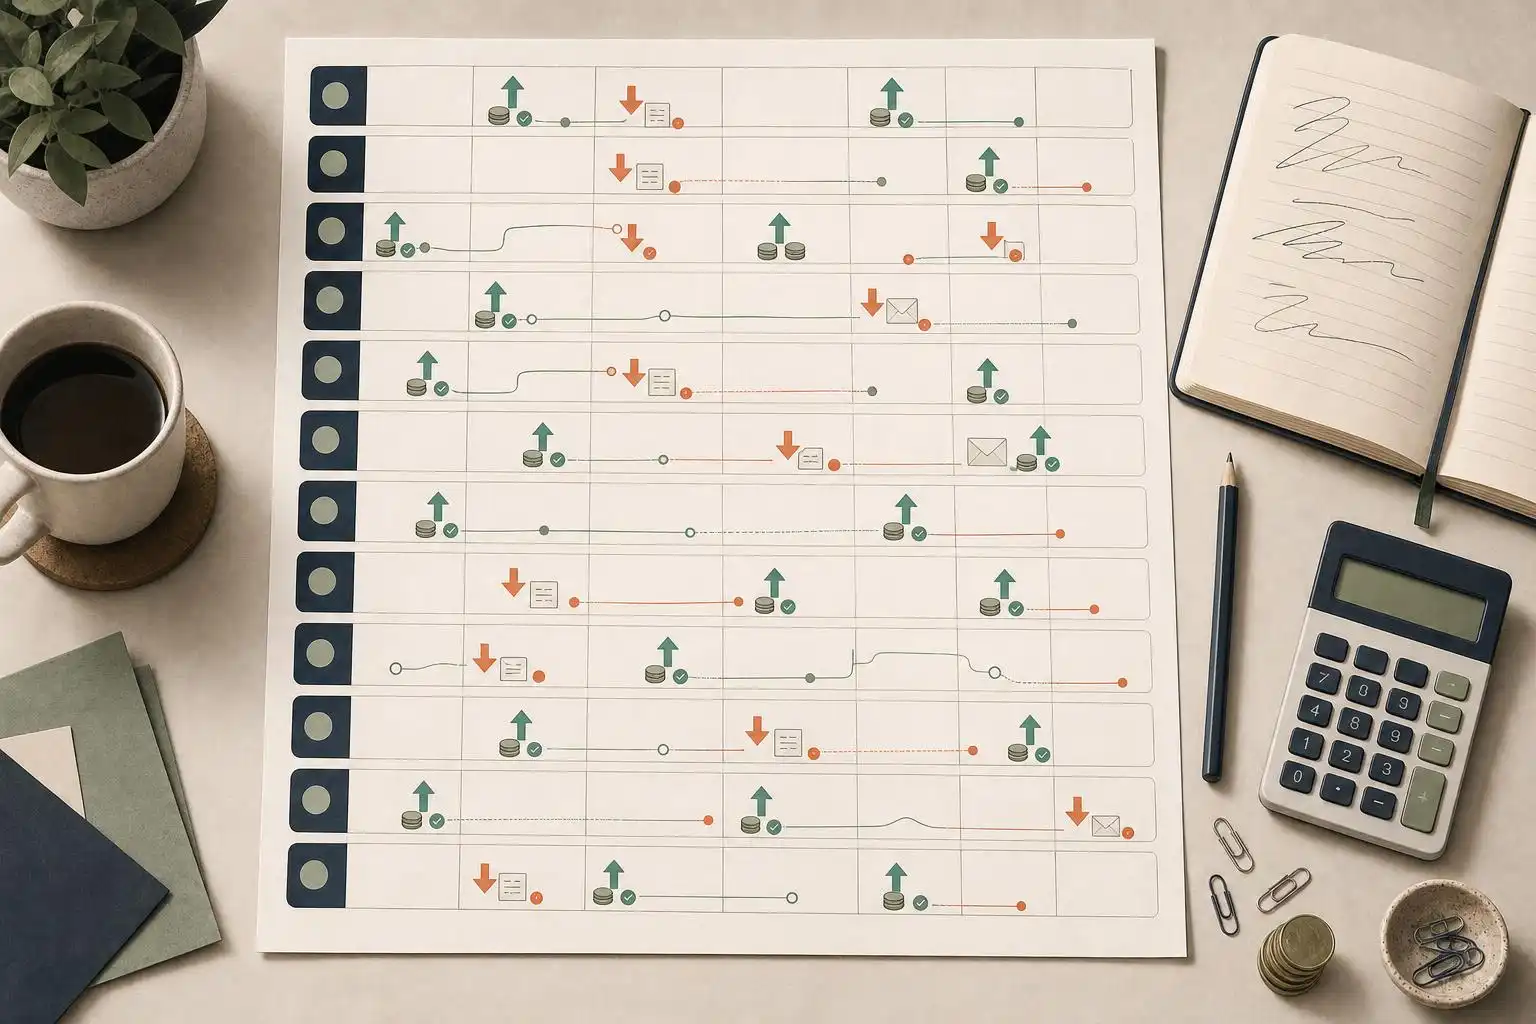
The goal is not to pressure good customers or demand annual prepayment from everyone. It is to know when money will arrive, make payment easy, and avoid committing cash you have not collected. Here is the operating system I would use for a small software business.
Build a cash calendar, not just a revenue dashboard
Monthly recurring revenue tells you what customers have agreed to pay. It does not tell you when the bank balance will change. Make a rolling 13-week cash calendar with a row for each week. Start with the current bank balance, then enter expected customer receipts and committed payments on their actual dates.
A simple sheet needs four columns: expected date, amount, counterparty, and confidence. A $400 card subscription due next Tuesday might be highly likely. A $12,000 invoice awaiting a customer’s purchase order is not, even if the deal is signed. Put uncertain receipts in a separate scenario rather than quietly counting them as cash.
Suppose you run a two-person SaaS business with $20,000 in MRR, $8,000 of monthly operating costs, and $35,000 in the bank. On paper, that is comfortable. But if $9,000 of the MRR comes from three customers who pay by invoice, and two invoices slip by a month, the next payroll cycle looks different. The useful question is not whether you are profitable in a typical month. It is whether your lowest projected bank balance is safe.
Update the calendar every Monday. Reconcile last week’s expected receipts against the bank statement, move late items to realistic dates, and look at the lowest balance in the next 13 weeks. If that balance approaches your minimum operating reserve, pause discretionary commitments before the shortfall becomes urgent. This is a more actionable trigger than waiting for a disappointing month-end report.
Make it easy for customers to pay you
Small companies sometimes treat invoicing as a final clerical step. A larger customer treats it as a process with rules. The person who bought your software may not be able to release a payment, and an invoice sent to that person’s inbox can sit there untouched.
Before promising an invoice-based customer a start date, establish the mechanics:
- Who receives invoices, and is there a dedicated billing address or portal?
- Is a purchase order required, and who obtains it?
- What exact entity name, tax details, and reference number must appear on the invoice?
- Does the payment clock begin on receipt, approval, or some later milestone?
Then send the invoice promptly. If a contract says payment is due 30 days after invoice receipt, waiting 12 days to issue it is effectively extending the customer’s terms to 42 days. For a $6,000 invoice, those 12 days may be worth more to your cash position than a small change in software costs.
Keep the invoice understandable to someone who never attended the sales call. Include the agreed service period, amount, due date, payment instructions, and the customer’s required reference. If the buyer needs a supplier form or security document before payment, handle that before the invoice is due—not on day 31.
Put payment terms in the deal, not in a follow-up email
A proposal that says only “$12,000 per year” leaves a crucial question unanswered: when does the $12,000 arrive? Payment terms belong in the written agreement alongside the scope and service dates. For a small vendor, “net 30 from invoice” and “net 60 after acceptance” create very different financing needs.
Consider a hypothetical $30,000 annual contract that requires $3,000 of onboarding work and $500 a month in incremental service costs. If the first payment arrives 60 days after launch, you may have spent $4,000 before collecting a dollar. Multiply that pattern across four new accounts and you have made a $16,000 working-capital commitment, whether or not you intended to.
When a customer requests a long payment window, first find out whether it is a hard procurement rule or a default on their template. If it is negotiable, ask for payment at signing or a shorter term. If it is not, look for another way to limit the cash gap: a narrower initial scope, an onboarding payment, or a start date that follows purchase-order approval. Get the final arrangement in writing before scheduling the work.
Do not accept a deal because its contract value is impressive while ignoring its funding requirement. A customer can be attractive over a year and still be unaffordable this quarter. If accommodating their terms would put your reserve below its floor, you need a different schedule or a different deal.
Separate collected money from spendable money
Annual prepayment can be powerful for a bootstrapper. A $12,000 payment today eliminates 12 monthly collection events and puts cash in the bank before you incur most of the service costs. But that deposit does not turn the entire $12,000 into available hiring money. You still owe the customer a year of service and may owe a refund under your terms or applicable law.
For internal planning, allocate an annual payment across the months it must support. If you collect $12,000 for 12 months, mark $1,000 per month as supporting future service. Keep a separate provision for expected refunds and applicable taxes. Your accounting treatment may differ depending on your jurisdiction and reporting basis; ask your accountant. The cash-management principle is simpler: do not spend tomorrow’s delivery money on today’s expansion.
The same distinction applies to sales tax, VAT, and similar amounts collected on behalf of tax authorities. They can make a bank balance look larger without increasing what the business can safely spend. Use a separate bank account or a clearly tracked ledger balance so a tax payment never arrives as a surprise.
Look closely at payment-processor timing, too. A card charge marked “paid” in your application may not reach your bank for several business days. Refunds, disputes, processor reserves, and fees can reduce the payout. Base the cash calendar on expected bank deposits, not the gross transactions shown in your billing tool.
Run collections as a calm, repeatable workflow
An overdue invoice is not always a dispute. Often it is an email sent to the wrong address, a missing purchase-order number, or a customer contact who changed roles. A consistent follow-up process finds those problems while they are still easy to fix.
Set a reminder before the due date, not just after it. For invoice customers, send a brief note confirming that accounts payable has the invoice and everything required to process it. If the due date passes, follow a documented sequence:
- On day 1 overdue, confirm receipt and ask whether anything is blocking payment.
- On day 7, follow up with the billing contact and copy your buyer if appropriate.
- On day 14, request a specific payment date and resolve any documented objection.
- On day 30, escalate to the decision-maker and apply the remedies your agreement allows.
Adjust those intervals to your customer relationships and contract. Do not threaten to shut off a critical service as a first move, and do not invent penalties that were never agreed. Your aim is to get a clear answer and preserve a good customer relationship while protecting the company’s cash.
For card payments, automate failed-payment notices and give customers a straightforward way to update a card. Then review unresolved failures personally at least once a week. A useful small-team division is for the billing system to send routine reminders while a founder handles high-value accounts or any case involving a genuine dispute. Automation should remove repetitive work, not become an excuse to ignore exceptions.
Track the number of overdue invoices and the dollars outstanding, especially beyond 30 days. Ten late $50 payments and one late $10,000 payment call for different responses. A weekly receivables review should end with a named next action for every material balance: who will contact whom, by when, and what answer they need.
Match commitments to money you can count on
Collection discipline matters most when it changes decisions. Suppose you expect a $15,000 customer payment and want to hire a contractor for a $5,000 project. If the work is optional, wait until the money clears. If it is necessary to deliver the customer’s contract, break the project into milestones you can fund from current cash or negotiate a customer payment tied to the first milestone.
This is not a case against contractors. It is a case against turning an uncertain receipt into a fixed obligation. Even a profitable business can run into trouble when it pays suppliers on Friday and customers pay next month. Small teams have an advantage here: they can reschedule work, narrow scope, and speak directly with buyers before a timing mismatch becomes a crisis.
Named bootstrapped companies such as 37signals and Balsamiq show that businesses can grow without making fundraising their default financing tool. Their paths are not templates for your collection terms. Your practical lesson is to make each new obligation affordable from your own cash cycle, rather than assuming the next sale—or a future round—will cover it.
Set a written rule for larger discretionary spending. For example: no new commitment over $2,000 unless the 13-week forecast remains above your minimum reserve without counting late invoices or unsigned deals. Your threshold will depend on your scale. The value is in deciding it ahead of time, when an exciting opportunity is not pushing you to treat hopeful money as certain money.
Give cash collection a weekly owner
You do not need a finance department. You need one person responsible for closing the loop between the billing system, the bank, and the work calendar. For a solo founder, that is you until the task is stable enough to delegate. In a tiny team, the owner can prepare the numbers while the founder remains accountable for exceptions and spending decisions.
Block 30 minutes each week to do four things:
- Match expected deposits against cash received.
- Send or assign follow-ups for material overdue balances.
- Update the lowest projected balance in the 13-week calendar.
- Delay, reduce, or approve upcoming commitments against that forecast.
Once a month, inspect the pattern rather than just the exceptions. Are particular customers consistently late? Are purchase orders slowing launches? Is your processor payout schedule longer than you assumed? Fix the recurring cause, not merely the latest invoice.
A signed contract is a promise. An issued invoice is a request. A bank deposit is cash you can use, subject to the obligations attached to it. Keep those three events distinct, and you can make calmer decisions about what to build, whom to hire, and how long your small company can stay independent.


Leave a Reply