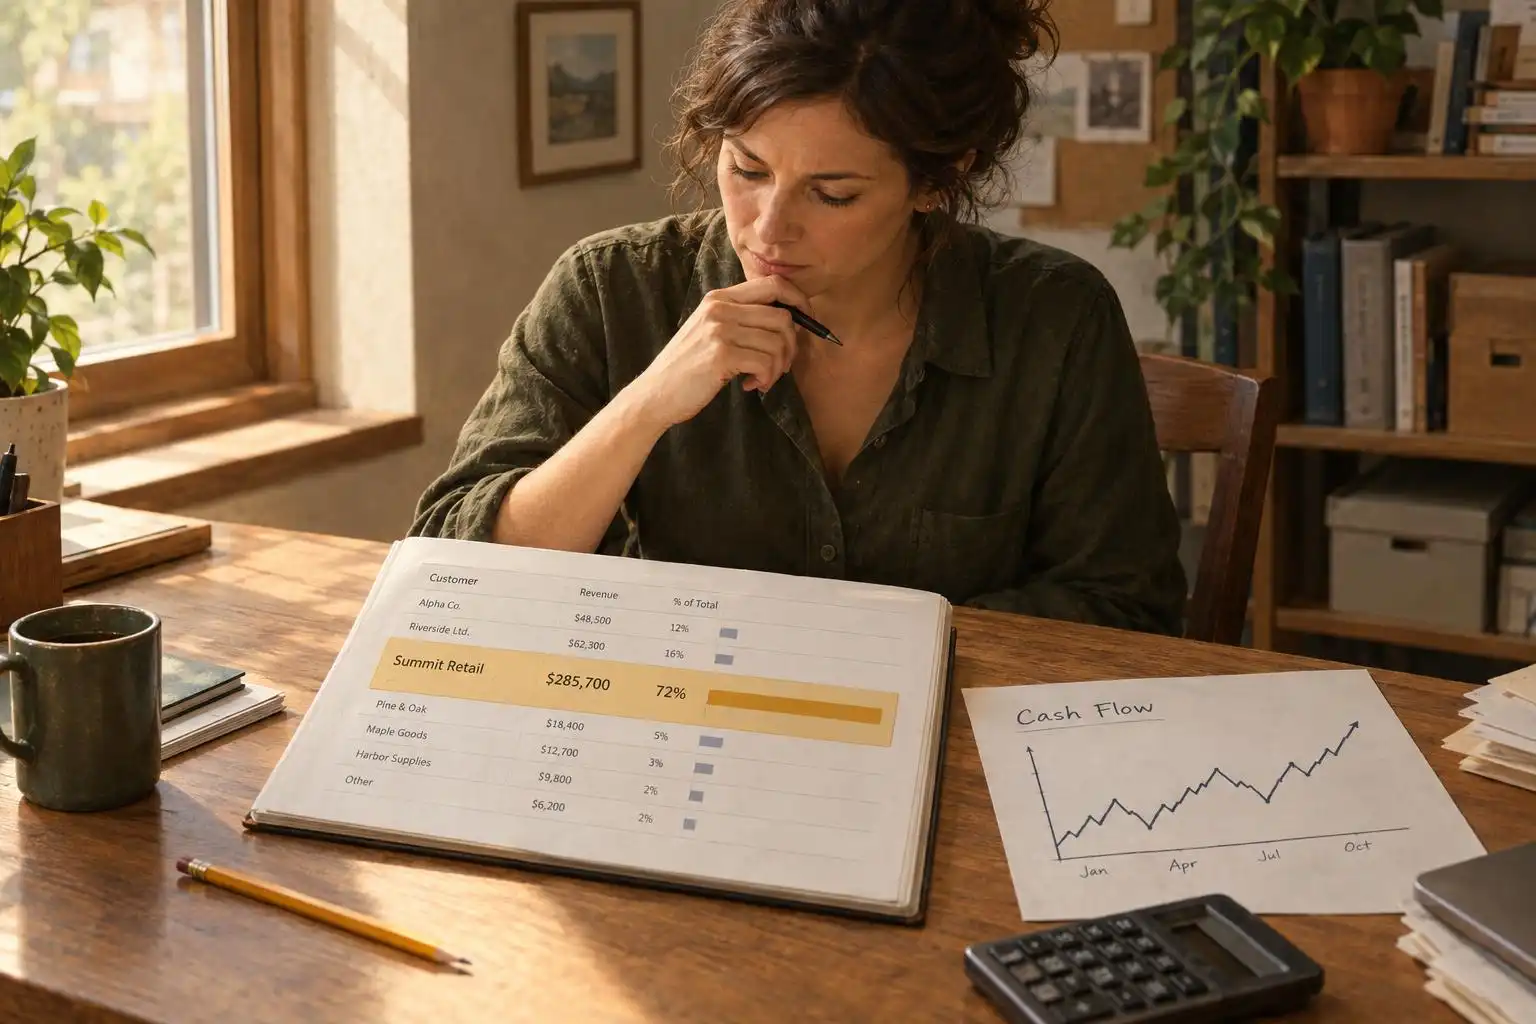

A large customer can make a bootstrapped business feel safe. Their invoice covers payroll. Their renewal makes next quarter look predictable. When they ask for a feature, it seems sensible to move them to the front of the queue.
Then the requests accumulate. Their procurement process changes your contract. Their support tickets interrupt every morning. A feature that only they use becomes the reason you cannot ship improvements for everyone else. You still own the company, but one customer is setting its priorities.
The problem is not that large customers are bad. It is that revenue concentration, unpaid obligations, and a crowded roadmap can turn one good account into a dependency. A tiny team needs a way to recognize that dependency before the next renewal forces a rushed decision.
Measure the dependency, not just the invoice
Start with collected revenue over the last three months, not the largest number in your sales pipeline. For each customer, calculate their share of collections and monthly recurring revenue separately. An annual prepayment can make this month’s bank balance look comfortable even though the account contributes a much smaller amount to each month’s economics.
Suppose your SaaS collects $24,000 a month, spends $16,000 on hosting, software, contractors, and a modest founder salary, and retains $8,000. Your largest customer pays $6,000 a month. They represent 25% of collections, but losing them does not cut your surplus by 25%. If costs stay fixed, surplus falls from $8,000 to $2,000: a 75% reduction. That is the number that should guide your decisions.
Now add $4,000 a month in contractor and support costs you took on to serve that account. If those costs cannot be removed quickly, losing the customer leaves you collecting $18,000 against $20,000 of expenses. You have gone from profitable to losing $2,000 a month. The apparent margin on the deal concealed its exit cost.
Keep a one-page concentration ledger. Update it monthly with these figures for your largest customers:
- Share of collected revenue and share of MRR
- Gross margin after account-specific expenses
- Founder and team hours spent on the account each month
- Months until renewal, and any payment or termination notice period
- Costs that remain for 30, 60, and 90 days after the customer leaves
There is no universal safe concentration percentage. For a two-person company, 20% of revenue from one account deserves attention; 40% may be perfectly workable for a short period if the contract is profitable and the work improves the core product. Treat those percentages as prompts to inspect the account, not as automatic reasons to reject it.
Price the time you cannot invoice
A demanding customer can consume capacity without creating a corresponding expense line. Put that time into the ledger. If two founders together spend 25 hours a month on one account, that is more than three working days unavailable for onboarding, reliability work, or sales. Assign an internal hourly cost even if neither founder draws an hourly wage. At $100 an hour, those 25 hours represent $2,500 of scarce capacity.
Do not confuse that internal figure with an invoice you must send. It is a decision tool. A $6,000-a-month account that requires $1,500 in infrastructure and contractors plus $2,500 of founder capacity may still be attractive. But its contribution is closer to $2,000 than $4,500. That distinction matters when you decide whether to accept another special request.
Track interruptions as well as hours. Ten predictable hours of scheduled implementation work may be easier to absorb than five hours scattered across urgent messages. For two weeks, log every account-specific request and note whether it was planned, whether another customer needed it, and what work it displaced. A support queue full of small exceptions can be harder to manage than one large project.
This is where staying small requires discipline rather than reflexive refusal. Bootstrapped product companies such as Balsamiq and 37signals demonstrate that a company can build a substantial business around a product used by many customers. Your version of that choice happens in ordinary calendar decisions: which request goes into the product, which becomes paid services work, and which gets a polite no.
Separate product improvements from private work
Before agreeing to a requested feature, write down who can use it besides the requesting customer. A bank-feed integration for one customer’s internal system is different from improving your import process so any customer can connect a common data source. Both might be worth doing, but they belong in different budgets.
I use a simple test: would we still want to maintain this feature if this customer left next month? If the answer is yes, it may be product development. If the answer is no, it is customer-specific work. Do not hide the latter in a general roadmap just because calling it a feature makes the deal feel scalable.
For customer-specific work, define a separate scope with a fee, a delivery date, an acceptance process, and a support boundary. Ask for a deposit or a paid first milestone before committing a month of build time. If a customer will not fund work that only they need, you have learned something useful before your team incurs the cost. Larger customers can be excellent partners when they pay for the extra work they create.
Preserve your ability to reuse what you learn. A customer may reasonably require confidentiality around its data and processes. That is different from owning the general-purpose improvements to your software. Have a qualified lawyer review material commitments, especially intellectual-property language, service levels, indemnities, and liability limits. A profitable-looking contract can become expensive when an obligation survives the project fee.
Put a time limit on experimental exceptions. You might agree to run a manual export for 60 days while testing whether a reusable export feature is worthwhile. Record who owns the task and what happens on day 61. Without an end date, temporary favors become permanent operating costs.
Keep the contract from spending next year’s cash
A signed annual contract is not twelve months of cash in the bank. If a customer pays monthly on net-60 terms, you may deliver roughly two months of service before the first payment arrives. At $6,000 a month, that is about $12,000 of receivables tied to one account. You still owe your team and vendors during those two months.
When you have leverage, ask for annual or quarterly payment in advance, or for a deposit that covers account-specific setup. If the buyer’s procurement rules prevent that, model the working-capital gap before signing. A deal can be profitable on paper and still strain the checking account during implementation.
Watch for commitments that change the business beyond payment terms. A 24-hour response guarantee may require weekend coverage. A custom security questionnaire may be a reasonable one-time task; a promise to implement every future control is not. A broad termination-for-convenience clause may leave you holding unrecovered setup costs. Negotiate specific obligations you can actually deliver, and ask counsel to review the final language.
For an annual prepayment, spread the cash across the months it must support. If a customer wires $72,000 in January for a year of service, transfer or earmark $6,000 a month for operating use rather than treating all $72,000 as January’s surplus. The unearned portion has work attached to it. Spending it on a permanent hire before you know whether the customer will renew is a particularly costly way to mistake timing for growth.
Build an exit plan while the relationship is healthy
Imagine receiving a nonrenewal notice today. What would you stop paying for immediately? Which contractor commitments run another two months? Could the remaining customers cover the founder’s salary? Answer those questions once a quarter, before emotion enters the conversation.
Run two versions of the test. In the first, the largest customer leaves at renewal. In the second, they stop paying while you continue service during a dispute. The second case exposes both cash risk and operational risk. Write down the dates when you can reduce costs, not merely the amounts you hope to save.
Make replacement revenue a steady activity rather than an emergency campaign. If one account is 30% of MRR, you do not need to replace it with another account of the same size. Ten customers at 3% each can leave you with a healthier business, even if finding and serving them takes longer. Give the team a modest, repeatable acquisition commitment—perhaps four hours a week on referrals, content, or partner conversations—that continues while the big customer is happy.
Keep the relationship healthy too. An exit plan is not a reason to neglect your largest customer. Give them a reliable contact, clear response windows, and honest updates about requests you will not take on. Customers are often easier to serve when they know where the boundaries are than when every request receives an uncertain maybe.
Decide what you are willing to trade
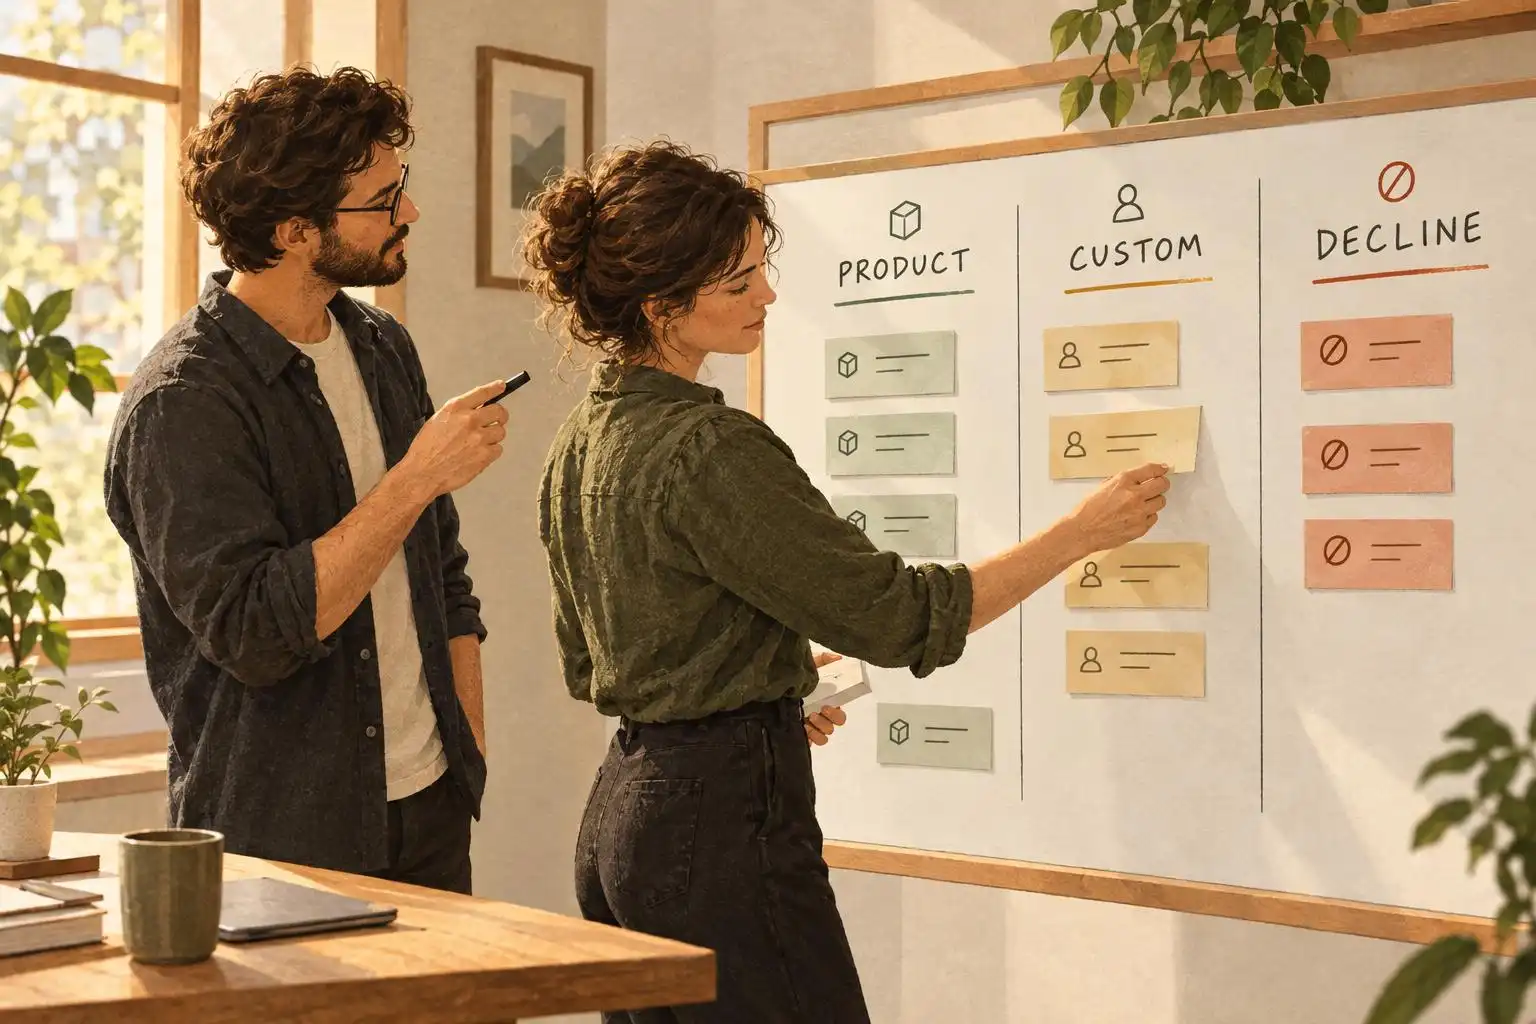
When a major customer asks for something outside the product, do not answer from the excitement of the contract or the fear of losing it. Pause long enough to produce a short decision memo. State the expected cash collections, direct expenses, founder hours, contract risks, and what will be delayed. Then choose deliberately among three responses:
- Build it into the product because multiple customers need it and you can support it indefinitely.
- Sell it as bounded, separately funded work with a clear end date.
- Decline it because the cash does not compensate for the dependency it creates.
For example, a customer offering $30,000 for a custom integration may look impossible to refuse. If it requires 200 founder hours, $5,000 in contractor help, and $500 a month in ongoing maintenance, the first-year commitment is much larger than the headline fee suggests. The right answer might be a paid discovery phase and a revised scope. It might be a no. What matters is that you make the choice with the maintenance bill visible.
A big customer should help finance a stronger company, not quietly become its operating system. Measure the account’s real contribution, fund exceptions explicitly, and maintain a credible path forward without it. Those habits let you appreciate the revenue while keeping the freedom you built the business to have.


Leave a Reply
You must be logged in to post a comment.